
Update (2026): Cashrewards closed in September 2025. If you want free cashback, use ShopBack. ROOPON is a paid membership with partner discounts and FREE included prize-draw entries — not a cashback clone.
Finding a cashback rewards app that delivers consistent Australian retailer offers without locking savings behind paid membership walls is harder than necessary. Too many apps force members to pay upfront or restrict cashback access to select partners, undermining real-world value for everyday spending. This comparison covers fees, app features, and payout structures across six alternatives so you can match the right cashback option to your regular purchases.
Table of contents
Roopon
At a glance
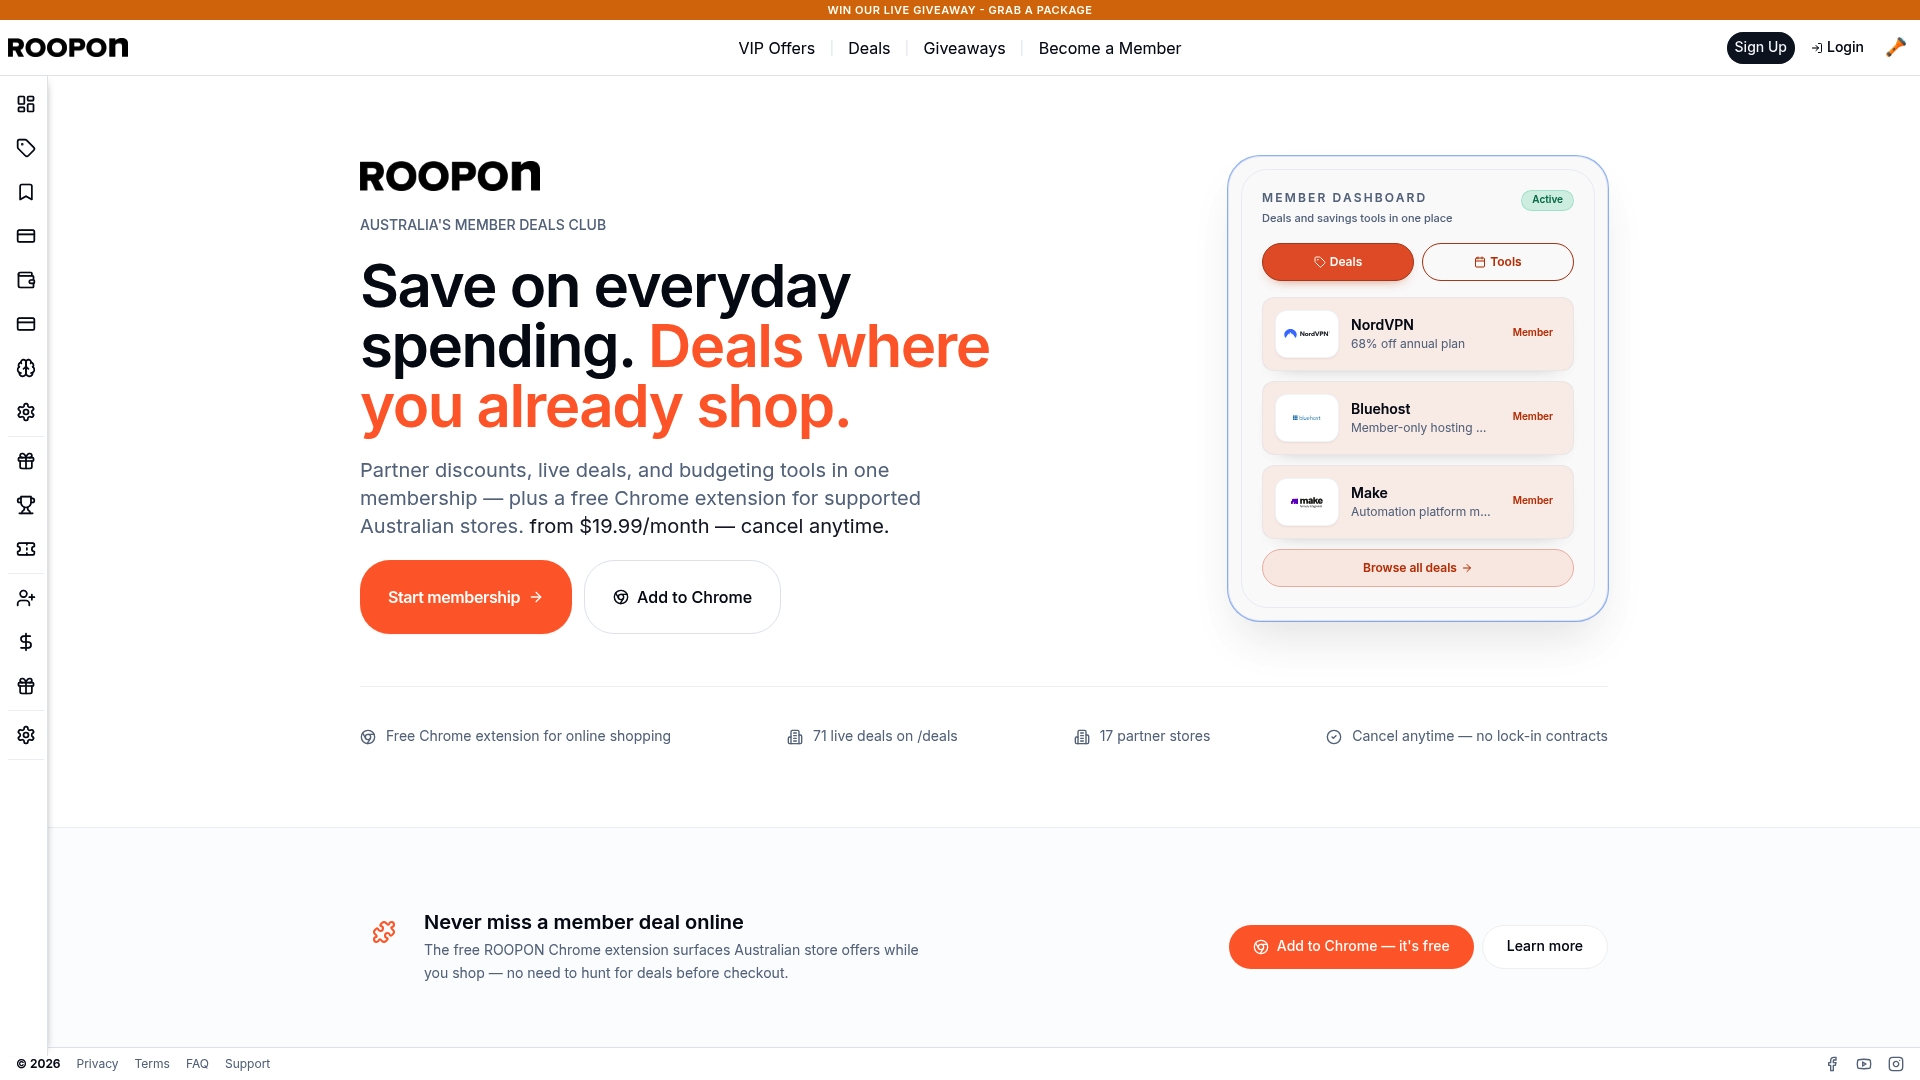
FREE Prize-draw entries follow the plan and that campaign’s terms. This page does not state odds. The service pairs membership discounts from over 16 partner stores with a Chrome extension that surfaces deals while you shop. Members also get budgeting tools and referral bonuses tied to FREE prize entries.
Core features
Roopon centres on member deals across everyday categories. It offers deal browsing for electronics, travel, groceries, and more. The platform includes a free Chrome extension that shows Australian store offers as you browse. Members can use budgeting and savings tools, and the platform highlights partner discounts for services like VPN and hosting.
Key differentiator
Roopon blends a paid membership club with in‑browser deal surfacing and built‑in savings tools. The combination means you see discounted prices while you shop and can track savings with budgeting features. That mix is aimed at turning occasional bargains into sustained monthly savings for Australians.
Pros
-
Access to discounts from over 16 partner stores makes it simple to find better prices on common purchases. The partner breadth covers retail and service categories.
-
The Chrome extension finds deals automatically while you browse. That cuts the time you spend hunting voucher codes and price matches.
-
Budgeting and savings tools help you plan when to spend and when to save. These tools include mechanisms to allocate payday funds for planned purchases.
-
Membership includes referral bonuses that add extra FREE entries to prize drawings. Those FREE bonus entries can improve your chances if you actively refer friends.
-
No lock‑in contracts let you cancel anytime. The membership model runs month to month which suits tight budgets.
Cons
- Requires an active membership for any access to deals and tools, so nothing is visible without signing up.
Who it's for
Roopon fits Australian shoppers who buy online regularly and want a single place for discounts and budgeting. It suits people who value small regular savings over time and who will use a browser extension. It is less useful for international shoppers or occasional buyers.
Unique value proposition
FREE Automatic entries into weekly prize drawings combine with exclusive 'mates rates' and referral bonuses to give members multiple ways to gain value. The platform pairs visible savings at checkout with tools such as the Payday Allocator to help you schedule spending. For budget conscious members this shifts savings from ad hoc catches to planned outcomes.
Real world use case
A member installs the Chrome extension before buying a laptop. The extension surfaces an exclusive discount from a partner store. The member applies the discount, logs the saving in the budgeting tool, and allocates a portion of their next payday using the Payday Allocator. FREE Referral entries later increase their chances in the weekly drawing.
Website: https://roopon.com
PokitPal
At a glance
Product-level cashback that targets specific SKUs is a standout claim from PokitPal. The vendor advertises card linked offers, real-time cashback and open banking connections as core capabilities. This review treats those statements as vendor self-reports and evaluates practical fit for banks, publishers and retailers.
Core features
- Card linked offers and discounts tied directly to customers' payment cards for automatic redemption.
- Real-time cashback that the vendor describes as applying at purchase without manual vouchers or codes.
- Open banking integration for automatic payment data and savings insights with read only access controls.
- Product level offers for targeted campaigns, letting merchants focus on specific SKUs rather than store wide deals.
- Anonymous transaction monitoring that gives users control over what is shared while supporting tailored rewards.
Key differentiator
PokitPal’s main angle is deep open banking connections used to trigger precise, personalised offers at the point of sale. That setup aims to let advertisers and banks match merchant funded rewards to actual purchases. The claim above points to tighter targeting than broad coupon programmes and therefore higher relevance per offer.
Pros
-
Offers a wide range of brand offers and discounts. This is useful if you want campaign reach across global and local merchants.
-
Supports secure open banking links with read only access. That model reduces friction for customers while keeping control over sensitive data.
-
Enables automatic cashback and savings without manual rebate claims. For consumers this removes steps between purchase and reward.
-
Allows product level targeting for campaigns. Brands can nudge purchases of specific SKUs rather than relying on generic discounts.
-
Interface and APIs are presented as easy to use for both consumer apps and partner integrations. That speeds up rollout for banks and publishers.
Cons
-
There are no specific third party user reviews cited. That makes independent assessment of reliability harder.
-
Public feedback and ratings are limited. Decision makers must accept a degree of uncertainty about long term performance.
-
Organisations requiring direct bespoke bank integrations should verify technical compatibility. Some banks have unique APIs or security rules that need custom work.
Who it's for
PokitPal suits financial institutions, publishers and retailers that want merchant funded rewards tied to actual card spend. It also fits teams that can operate with an API led integration and that value targeted SKU level campaigns. Budget conscious partners should confirm technical fit before committing.
Real world use case
A retail chain uses PokitPal to run SKU specific cashback. The retailer funds product level offers and the bank pushes personalised discounts into its banking app. Customers receive cashback automatically when their card matches the promoted SKU at checkout.
Pricing
Public pricing is listed as not applicable. The vendor does not publish standard consumer tier prices. Contact PokitPal for commercial terms and API licence details.
Website: https://pokitpal.com
Aura
At a glance
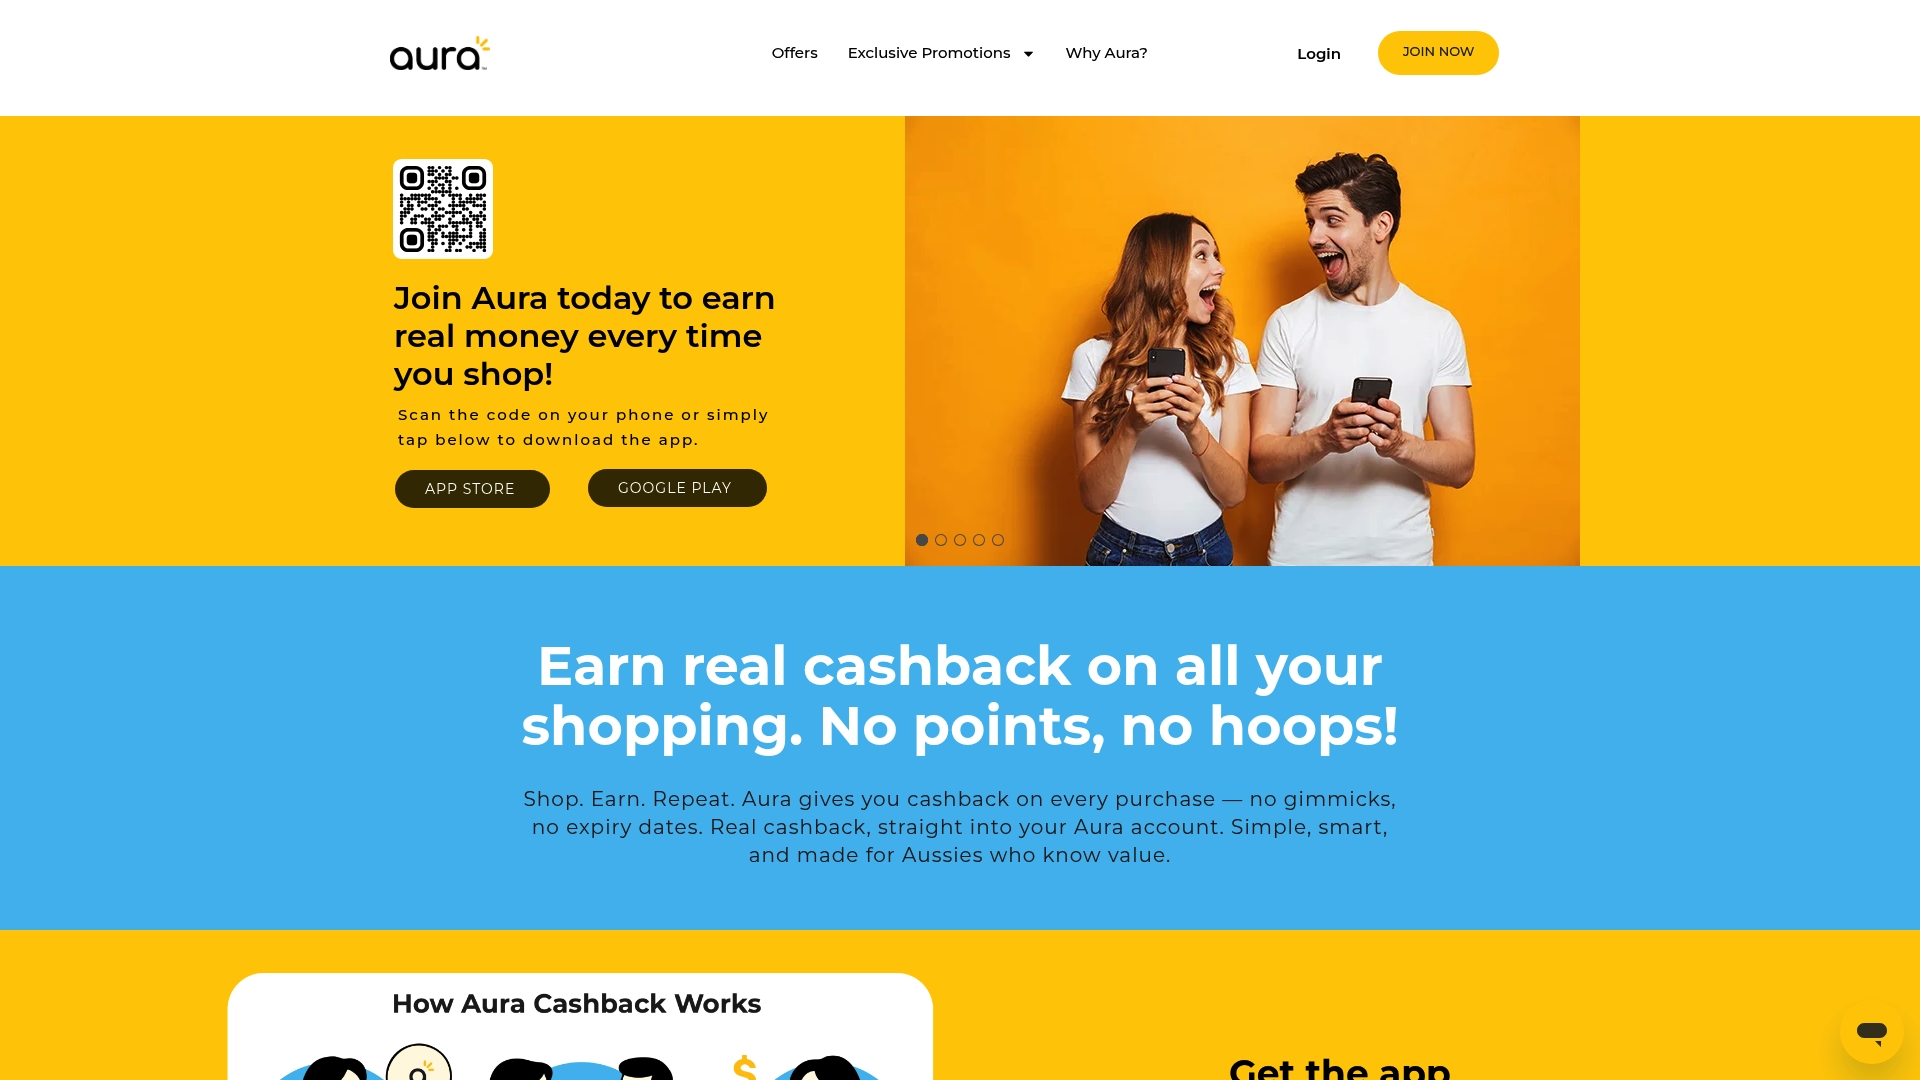
According to the company, Aura connects members to over 1,000 cashback offers. That breadth means many everyday stores and services appear among eligible partners. For budget conscious Australians, this can turn routine spending into small, regular cash back that accumulates over time.
Core features
Aura centres on card linked rewards that credit cash back automatically when you use a linked debit or credit card.
- Card linked cashback: Link Visa or Mastercard and earn on in store and online purchases.
- Large retail partnerships: Works with major names including Woolworths, Coles, Virgin Australia, and The Iconic.
- Gift card cashback: Buy gift cards and receive cash back into your Aura account.
- Insurance and investment offers: Cashback for partner insurance products and selected investment or refinancing services from providers such as Ezicover and Resolve.
Key differentiator
Aura pays actual cash back rather than points or store credit. This direct payout model suits people who want clear, spendable returns from everyday transactions. It targets straightforward card linked reward earning rather than membership discounts or prize draws used by some competitors such as Roopon.
Pros
- Simple account setup and card linking makes earning passive. The app guides the process so you do not need merchant codes.
- Extensive partner list increases the chance you will hit offers during routine shopping trips. That variety maps well to grocery and travel spend.
- No fees for members: Rewards are paid as cash and the platform is free to join. This keeps the math clear for budget planners.
- Option to route some cashback to charities adds a social angle. Members can support community groups while saving.
- Gift card and insurance cashback broaden where you can earn beyond groceries and retail.
Cons
- Several users report slow responses from customer support. That can be frustrating when a cashback transaction is missing.
- Some members describe difficulty cancelling subscriptions or linked services via the app. This suggests account management could be smoother.
- Cashback timing is inconsistent for a few merchants. Delays may occur around bank holidays and weekends.
When it may not fit
Aura is limited to Australians with Australian debit or credit cards for the card linked offers. If you prefer loyalty points or store credit, the cash model may feel less flexible for certain rewards. Also, if you need guaranteed same day payouts, Aura may not fit because some cashback transfers depend on banking hours.
Who it's for
Australian shoppers who want direct cash back from everyday spending will like Aura. It suits people comfortable linking their bank card and who prefer clear cash rewards over points. Those who want to direct a portion of rewards to charity will find a useful option here.
Real world use case
A shopper links a Visa card to Aura, buys weekly groceries at Woolworths, fills fuel, and purchases a gift card for a birthday. Cashback posts to the Aura account, and the member moves a portion as a donation to a local community group.
Website: https://aura.club
Paylab
At a glance
Over 140 Australian retailers participate in Paylab's rewards and cashback network. The app combines instant rewards, digital gift cards, and wage access tools for employees. That mix makes Paylab stand out for users who want savings and short-term cash flow options in one place.
Core features
Paylab bundles retail rewards with employee-focused financial tools. The mobile app tracks and stores rewards for later use.
- Earn rewards and cashback at participating Australian stores for everyday shopping and dining.
- Digital gift cards available instantly for online and in-store use, so savings are usable right away.
- Multiple payment methods supported, including linked debit or credit cards, Apple Pay, and Google Pay.
- Paylab Advance and RentPay let employees access wages early or use rewards to offset rent and donations.
Key differentiator
Paylab pairs retail cashback with employer-facing wage access and rent payment features. That combination targets employees as both shoppers and benefit recipients. It is narrower than pure cashback apps but more useful for staff who need short-term wage access and everyday discounts.
Pros
-
Offers instant rewards and cashback at major Australian stores. This turns routine shopping into small, immediate savings.
-
Lets you buy and use digital gift cards instantly. That keeps rewards practical for gifts or quick purchases.
-
Supports Apple Pay, Google Pay, and linked cards for straightforward payments. The options reduce friction at checkout.
-
Includes wage access through Paylab Advance, which helps with cash flow before payday. Employers can offer this as an employee perk.
-
Allows rewards to offset rent payments and to be donated to charity. That adds flexibility beyond standard cashback use.
Cons
-
No third-party reviews are available. That leaves user satisfaction and long term reliability unclear.
-
Fee information for some transactions is not transparent. Card processing surcharges and gift card fees lack clear public detail.
-
Documentation on limits and redemption rules is sparse. Users may need to contact support to clarify specific restrictions.
When it may not fit
If you want a cashback app with widely published user ratings this is not ideal. The platform lacks independent reviews and clear fee tables. If precise fee and redemption rules matter for your budgeting, choose a service with full public transparency instead.
Who it's for
Consumers who shop regularly at Australian partner stores and want immediate savings will find value. Employees who need occasional wage access or whose employer offers Paylab benefits will gain the most. Small employers seeking an extra staff perk can also use Paylab as a benefits add on.
Real world use case
A shopper uses Paylab to buy weekend groceries at a partner supermarket, earning instant cashback stored in the app. Later they buy a digital gift card for a birthday present using those rewards. If bills are tight the same user can access a small wage advance through Paylab Advance to cover an unexpected cost.
Pricing
Paylab is free to join and use for rewards tracking and gift card purchases. The vendor states a surcharge applies for payment processing through credit or debit cards. Check card processing fees before using card payments for large purchases.
Website: https://paylab.com.au
Cents2
At a glance
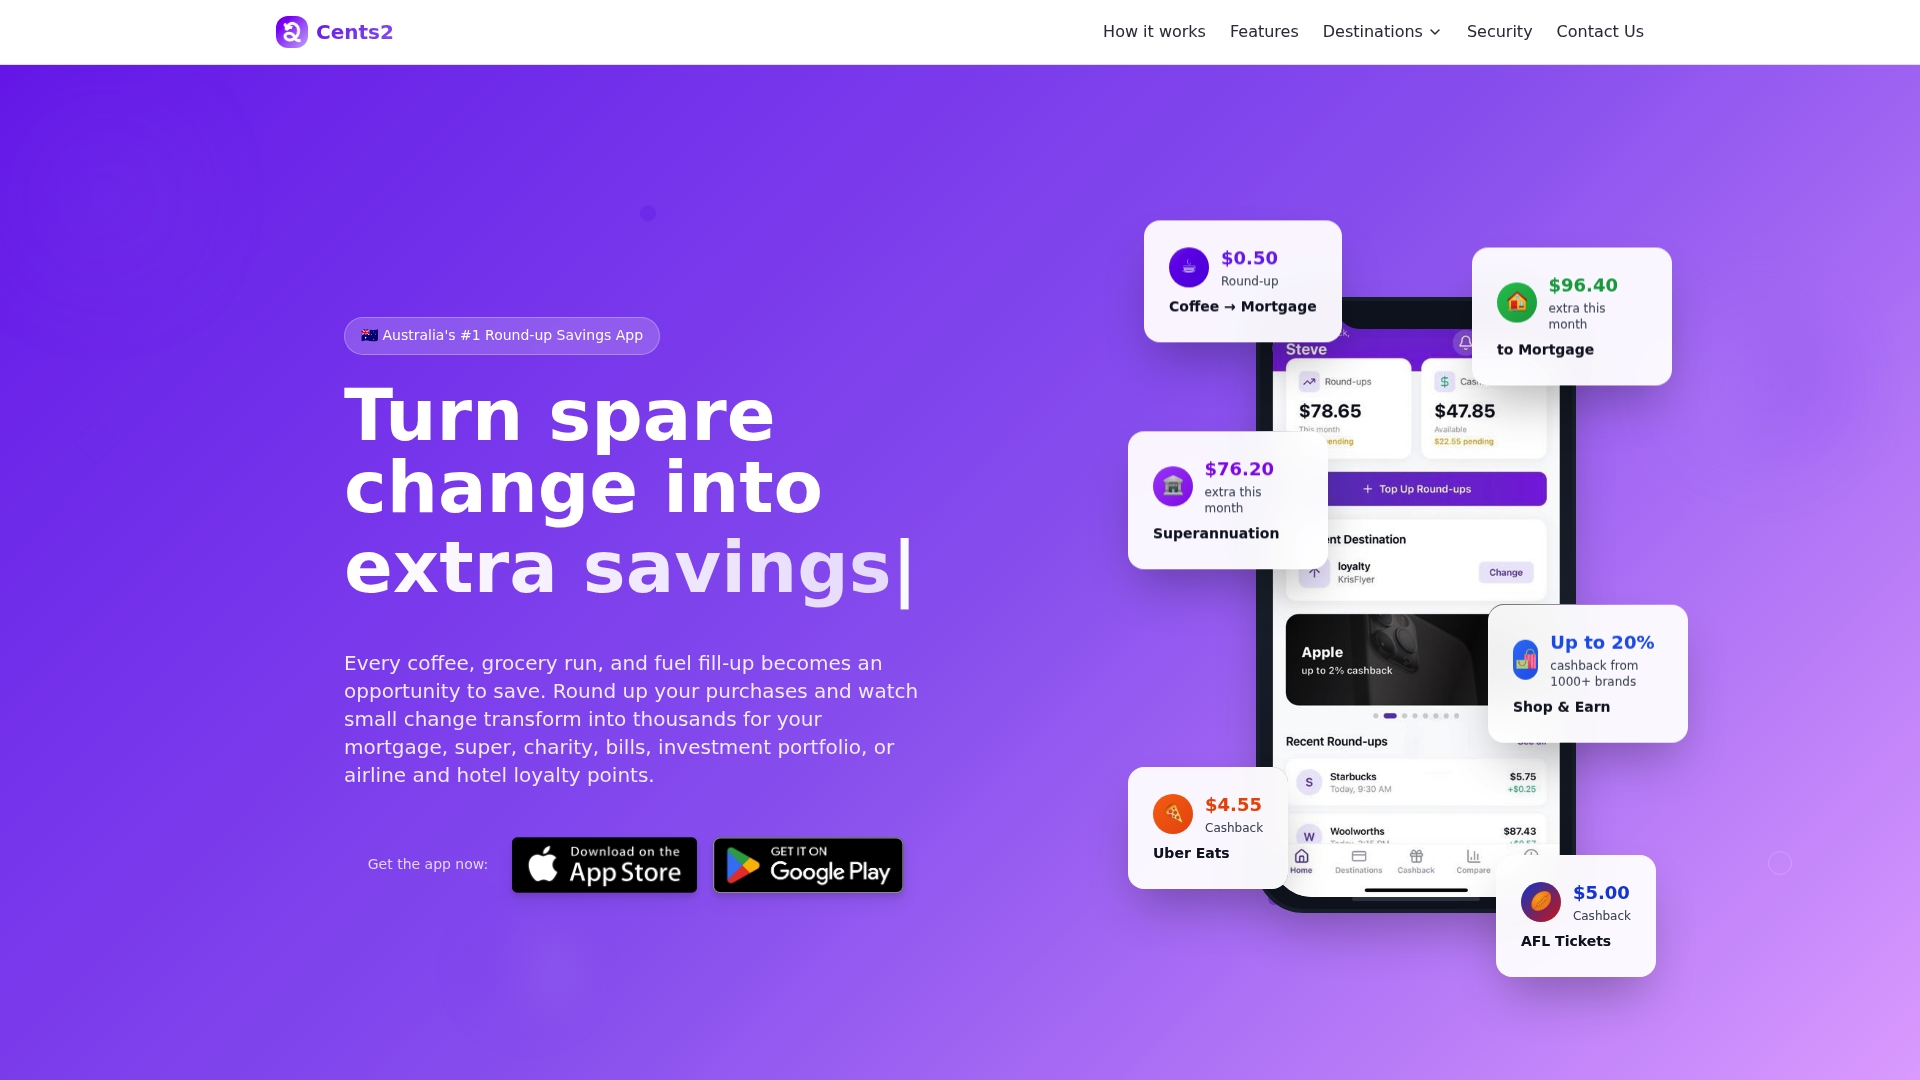
The vendor claims it is Australia’s #1 round up savings app. That claim highlights its focus on turning spare change into measurable progress toward goals. The app links bank accounts using open banking and directs round ups to mortgages, superannuation, charity, investments, or bills. This makes small, frequent transactions a steady savings habit for people who prefer set and forget finance tools.
Core features
- Automatic round ups on everyday purchases that collect spare change and move it to chosen destinations.
- Cashback rewards through partner brands to add extra savings on top of round ups.
- Customisable destinations for savings including mortgage, superannuation, charity, investments, bills and loyalty points.
- Flexible controls to pause or change round up settings and destination splits.
- Tiered plans with a free option and a paid Full Access plan that adds auto investments and cashback integrations.
Key differentiator
Cents2 aims squarely at automated round up saving and directing small amounts into multiple financial destinations. Its strength is the breadth of destination options and user controlled customisation. Compared with Roopon, Cents2 serves people who want automatic micro contributions instead of membership discounts plus FREE prize entries. The model suits steady accumulation rather than reward hunting.
Pros
-
Widely supported destinations for small contributions. Users can split round ups across mortgage, superannuation, charity, investments or bills to match personal priorities.
-
No lock in contracts and simple plan choices. The free tier allows trial before paying for extra features.
-
Secure bank linking via open banking and encryption. That reduces manual transfers and keeps round ups automated.
-
User controlled customisation of round up settings. You can pause or adjust round ups to fit irregular cash flow.
-
Supports multiple asset classes and partnerships with brands for extra cashback. That adds upside beyond simple savings.
Cons
-
Independent user reviews are scarce. The lack of substantive third party feedback makes real world experience harder to verify.
-
Most feature claims come from vendor material. Financial impacts and earnings are not validated by independent sources.
-
The app’s strengths depend on partner offers. If cashback deals change, the effective return to users will vary.
Who it's for
Australian users who prefer a low effort way to save and invest are the best fit. Cents2 suits someone who wants spare change directed automatically into a mortgage top up, superannuation, charity giving, or small investments. It fits people who favour steady accumulation over active reward chasing.
Real world use case
A user links their bank account then sets mortgage and super as destinations. Every card purchase triggers round ups that the app pools and transfers monthly. Over months the small contributions reduce mortgage principal or boost super, while occasional cashback offers add extra value.
Pricing
Free tier available for basic round up features. Paid Full Access $3.50/month billed monthly adds auto investments and cashback integrations. The subscription is deducted from round ups by default so you do not need a separate payment method.
Website: https://cents2.com.au
Cashbac
At a glance
The vendor advertises more than 1,000 merchant locations where users can earn points at the point of sale. Cashbac focuses on instant point crediting after transactions. That immediacy makes it useful for shoppers who want visible rewards without waiting.
Core features
Cashbac centres on earning and redeeming points at participating merchants. The app works on Android and iOS and links with payment cards for extra points.
- Instant rewards: points credited immediately after qualifying transactions.
- Card linking: connect credit, debit, or e-money cards for multipliers.
- Location-based suggestions: finds promos nearby automatically.
- Secure checkout with PIN and 3-D Secure.
- Referral system for additional reward FREE entries.
Key differentiator
Cashbac pairs card linkage with live location signals to suggest nearby deals as you travel. That means you can rely on your existing cards to maximise multipliers without scanning codes. The live promo suggestions make savings practical when you are out and about.
Pros
-
Ease of earning and redeeming rewards instantly. You see points after a purchase, so the value feels immediate.
-
Location-based promo suggestions enhance savings. The app surfaces nearby offers, which helps you decide where to spend.
-
Multiple rewards through card linking. Linking Visa or Mastercard can unlock extra point multipliers without extra steps.
-
Secure in-app procedures. PIN protection and a 3-D Secure flow reduce fraud risk during card transactions.
-
Simple discovery for deals. Finding partner merchants nearby is straightforward and saves time when shopping.
Cons
-
No substantive third-party user reviews available, limiting independent validation of the experience.
-
Limited published information on customer support and app stability. That makes recovery options unclear after errors.
-
No detailed public information on point values or expiry rules. It is hard to judge actual cash-equivalent value.
-
The referral model is described but specifics of bonus amounts and caps are not clear in the materials.
When it may not fit
If you need transparent point valuation before signing up, this app may frustrate you. Frequent travellers who rely on large loyalty programmes might find partner coverage patchy. Organisations wanting enterprise reporting or business dashboards will need a different tool.
Notable integrations
Cashbac integrates the 3-D Secure process for card security. The app also links directly to users’ credit, debit, and e-money cards to apply multipliers and credit points automatically.
Who it's for
Cashbac fits consumers who shop regularly at partner merchants and want immediate rewards credited at the point of sale. It suits people who prefer using their existing cards rather than carrying separate vouchers or loyalty cards. Budget-conscious Australians who like local dining and retail deals will get the most value.
Real world use case
A user links a Visa card to Cashbac and visits a partner coffee shop. They tap the phone on a beacon device to complete payment. Points arrive instantly and can be used on the next coffee or saved for a larger redemption.
Pricing
The product listing states: Not applicable — informational only. There is no tiered pricing described in the materials provided. Any fees, if present, would appear in the app or partner terms.
Website: https://cashbac.com
Comparison of alternatives
With so many options available, selecting the most suitable cashback platform depends on your preferences for features such as reward integration, types of benefits, or cost of access. In this comparison, we will explore several alternatives to understand their unique advantages and how they meet different user needs.
Feature comparison: integration and flexibility
Roopon features a approach combining membership-based discounts, browser-integrated deal discovery, and budgeting tools to help manage finances. The intuitive interface and automation in deal discovery are tailored for regular online shoppers. PokitPal, in comparison, focuses on providing real-time, product-level cashback through open banking integration. This allows for highly targeted offers, making it ideal for initiatives requiring customer behavioural analysis and precise marketing efforts. Meanwhile, Cents2 distinguishes itself with an automatic round-up feature for financial savings, accommodating individuals seeking hands-off methods to allocate small transactions into long-term savings.
Strength analysis: reward structures and target audience
Regarding reward delivery, Aura stands out due to the extensive network of over 1,000 cashback partnerships, reinforcing its capabilities for those looking to maximise day-to-day savings. In contrast, Paylab extends functionalities beyond mere savings, integrating employer-related financial support tools such as wage advancement. Cashbac is dedicated to providing immediate rewards points credited after transactions, catering to users who prioritise real-time benefit realisations during their purchases.
Best fit
- Roopon is ideal for Australians who make frequent online purchases and appreciate having budgeting tools accompany their cashback discovery.
- PokitPal serves scenarios involving precise targeting for cashback offers for specific product categories, aiding businesses with tailored campaigns.
- Aura appeals more to those who want reliable and high-volume cashback from a broad network of partner merchants.
- Paylab is valuable for employers looking to provide their employees with financial wellness tools and integrated reward options.
- Cents2 is suited for users prioritising automated small-scale savings channelled towards long-term goals such as mortgages or superannuation.
Our pick
Given the information analysed, Roopon emerges as a compelling option for those prioritising an all-in-one solution with exceptional odds for prize drawings, partnered retailer discounts, and accessible financial management tools. However, individuals looking for immediate gratification through instant points or cashback should consider alternatives such as Aura or Cashbac to better suit their needs and preferences.
Discover a concise comparison of alternatives to the cashback app site by evaluating their unique features, target audiences, and more.
| Product | Core Feature | Key Differentiator | Best For | Pricing | Notable Limitation |
|---|---|---|---|---|---|
| Roopon | Member deals, Chrome extension | Discounts with budgeting tools | Australian online shoppers | Not disclosed | Requires membership for access |
| PokitPal | Real-time cashback with banking links | Deep open banking integration for tailored offers | Institutions valuing precise targeting | Not disclosed | Lacks public performance reviews |
| Aura | Card linked cashback | Pays direct cash over points | Users seeking clear cash rewards | Free | Slow support responsiveness reported |
| Paylab | Cashback with wage access features | Employee-focused perks with payment flexibility | Regular shoppers needing wage advance | Free | Minimal information on fee structures |
| Cents2 | Savings with roundup feature | Directed micro-savings to multiple goals | Automated savers | Free/$3.50/mo | Lack of independent user reviews |
| Cashbac | Instant reward points at payment | Location-based deal recommendations | Savings during local dining and shopping | Not applicable | Limited partner merchant information available |
Boost your savings beyond thecashbackapp.com alternatives
Finding dependable rewards with better odds can feel like chasing a needle in a haystack. FREE Prize-draw entries follow the plan and that campaign’s terms. This page does not state odds. This combination turns casual shopping into planned, effective saving with helpful budgeting tools like the Payday Allocator and FREE bonus referral entries.
Ready to move beyond typical cashback apps? Experience a practical way to maximise your savings and prizes with Roopon. Visit Roopon to explore how this membership model supports your budget and boosts your reward chances without lock-in contracts or guesswork.
FAQ
How does roopon’s membership model compare to other cashback apps?
Roopon operates on a monthly membership model that provides access to exclusive discounts from over 16 partner stores. This setup is designed to help members achieve sustained monthly savings, unlike some cashback apps that do not require a membership. Exploring Roopon could be worthwhile if you prefer a structured approach to saving consistently.
What is the difference between Roopon and PokitPal in terms of cashback capabilities?
PokitPal stands out with its card-linked offers that provide real-time cashback at the point of sale without the need for manual codes. In contrast, Roopon’s model focuses on memberships and discounts that enhance regular shopping savings. If your priority is instant rewards from everyday purchases, PokitPal might serve you better, while Roopon appeals more if you prefer leveraging discounts over time.
Can i use Roopon if i don’t shop frequently?
Roopon is best suited for regular online shoppers who will benefit from its blend of discounts, budgeting tools, and FREE prize entries. If you are an occasional buyer, you may not maximise its features and consider exploring options that cater specifically to infrequent purchases.
How does Roopon ensure better odds for winning prizes compared to competitors?
FREE Prize-draw entries follow the plan and that campaign’s terms. This page does not state odds.
What savings tools does Roopon offer that other cashback apps might not?
Roopon includes budgeting tools that assist members in planning their spending effectively, such as the Payday Allocator, which aids in allocating funds for desired purchases. These features provide a unique advantage for users looking to track their savings goals more efficiently.
