
TL;DR:
- Cash-equivalent rewards are incentives like prepaid cards, gift cards, or cashback credits that offer flexible spending power. They sit between cash and non-cash rewards, providing liquidity and a perceived higher value due to the endowment effect.
Cash-equivalent rewards are incentives that function like cash, giving recipients flexible purchasing power they can direct toward everyday expenses, savings, or debt reduction. Unlike a branded gift or a points balance locked to one retailer, cash-equivalent rewards include prepaid debit cards, gift cards redeemable across multiple merchants, and cashback credited directly to an account. They sit between pure cash and non-cash rewards on the incentive spectrum, and understanding that distinction matters for anyone trying to get more from their spending. The role of cash-equivalent rewards explained simply: they put real, usable value back in your hands, often with a psychological lift that plain cash does not deliver.
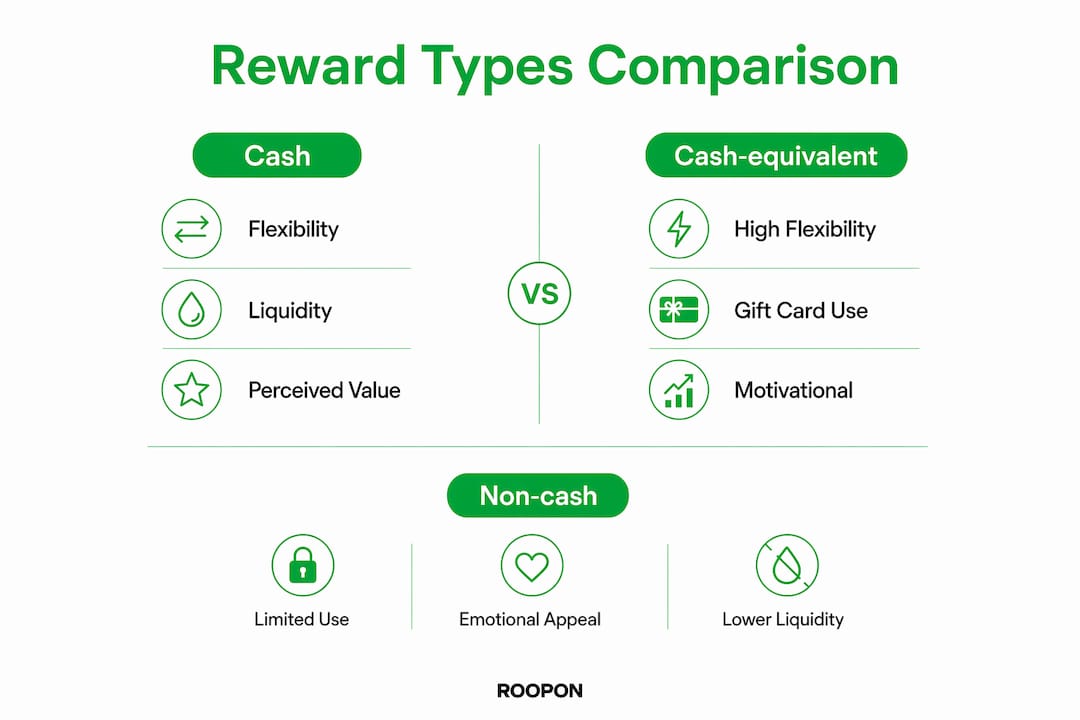
How do cash-equivalent rewards compare with cash and non-cash incentives?
Cash-equivalent rewards occupy a distinct position in the incentive world. Pure cash is maximally flexible but lacks emotional impact, blending into a recipient's regular income without leaving a memorable impression. Non-cash rewards like experiences or merchandise carry emotional weight but restrict how recipients use the value. Cash-equivalents sit in the middle, offering genuine liquidity while retaining a sense of separateness from ordinary wages.
The psychology behind this matters. Gift cards carry approximately 22% higher perceived value than their actual face value, a phenomenon behavioural economists call the endowment effect. That means a $50 prepaid card feels worth more than $50 in cash to the person receiving it, even though the spending power is nearly identical.
The table below compares the three reward types across the features that matter most to everyday savers.
| Feature | Cash | Cash-equivalent | Non-cash |
|---|---|---|---|
| Flexibility | Maximum | High | Low to moderate |
| Emotional impact | Low | Moderate | High |
| Perceived value boost | None | ~22% higher | Varies |
| Budgeting visibility | Low | Moderate | High |
| Tax treatment | Fully taxable | Usually taxable | May be exempt under thresholds |
Pro Tip: If you receive a prepaid reward card, treat it as a separate budget line rather than folding it into your everyday account. That separation preserves the psychological lift and makes it easier to direct the value intentionally.
What are the typical sources and examples of cash-equivalent rewards?
Cash-equivalent rewards appear across a wide range of everyday financial products. The most common source is the cash-back credit card, which returns 0.5% to 3% on most purchases, with select categories reaching up to 5%. Redemption thresholds are commonly set around $25, meaning you need to accumulate that amount before withdrawing the value.
Beyond credit cards, cash-equivalent rewards take several other forms:
- Prepaid debit cards loaded with a fixed dollar amount, redeemable anywhere the card network is accepted
- Gift cards issued by major retailers or multi-brand platforms, offering broad spending flexibility
- Statement credits applied directly against a card balance, reducing what you owe
- "Pay with points" features that convert loyalty points into cash value at the point of sale, connecting rewards directly to purchase moments and increasing behavioural impact
- Membership discount programmes like those offered by Roopon, which combine partner store discounts with cashback-style savings across over 16 retailers
- Cashback apps and browser extensions that return a percentage of online purchases automatically
Each format carries slightly different redemption rules, expiry conditions, and tax treatment. Knowing which type you hold determines how and when you can access the value.
Pro Tip: Check the expiry date on any prepaid or gift card reward the moment you receive it. Cards with 12-month expiry windows are common, and unused balances are simply lost.
What are the key benefits of cash-equivalent rewards for budgeting and savings?
Cash-equivalent rewards deliver four concrete benefits for anyone managing a personal budget.
-
Increased disposable income. Every dollar returned through cashback or a discount programme is a dollar you did not spend. Over a year of consistent spending on a 2% cashback card, a household spending $30,000 annually recovers $600 without changing its habits.
-
Budgeting flexibility. Because cash-equivalents are liquid, you can direct them toward whichever expense category needs attention that month. A statement credit reduces your card balance. A prepaid card covers a grocery run. That flexibility is something a merchandise reward simply cannot match.
-
Psychological windfall effect. Recipients tend to treat cashback and reward credits as "found money" rather than earned income. That framing encourages saving or debt repayment rather than routine spending, which is a genuine behavioural advantage for budget-conscious households.
-
Compounding value through programme stacking. Combining cashback with experiential rewards drives longer-term engagement and greater total value than relying on a single reward type. Roopon's model reflects this: members access exclusive discounts across partner stores while also earning automatic entries into weekly prize draws, stacking financial savings with the possibility of a larger cash win.
The importance of cash rewards in a personal finance plan is not just the dollar amount returned. It is the habit of redirecting that value intentionally, rather than letting it disappear into general spending.
What limitations and behavioural considerations affect the impact of cash-equivalent rewards?
Cash-equivalent rewards are not without real drawbacks. The most significant is invisibility. Cash incentives are absorbed into regular expenses, which undermines lasting motivation. When a $50 cashback credit lands in your account, it rarely feels like a reward. It just looks like a slightly lower balance.
Tax treatment adds another layer of complexity. Cash bonuses are fully taxable, and most cash-equivalent rewards received through employment or business programmes are treated the same way. Some non-cash gifts below $500 may fall outside taxable income depending on local guidelines, but prepaid cards and gift cards generally do not qualify for that exemption. The Australian Taxation Office applies similar principles to the IRS guidance that treats cash-equivalent rewards as taxable income, equivalent to wages for withholding purposes.
⚠️ Worth knowing: If you receive cash-equivalent rewards through an employer recognition programme, check with a registered tax agent about your reporting obligations. The tax treatment differs from consumer loyalty cashback, which is generally not assessable income in Australia.
The motivational gap is real too. Research confirms that cash lacks the behavioural impact needed for lasting behaviour change, unlike experiential or non-cash rewards. For personal finance goals that require sustained discipline, relying solely on cashback programmes may not be enough. Pairing them with visible, memorable rewards closes that gap.
How can individuals maximise the value of cash-equivalent rewards in 2026?
Getting the most from cash-equivalent rewards requires deliberate choices, not passive accumulation.
-
Track your redemption thresholds. Many cashback programmes require a minimum balance before you can withdraw. Set a calendar reminder when you are close to the threshold so you redeem promptly and avoid value sitting idle.
-
Combine reward types. Effective programmes blend cashback with "pay with points" and experiential options for sustained engagement. Choose programmes that offer more than one redemption pathway.
-
Use a budgeting tool to track reward income. Roopon's Payday Allocator is designed for exactly this purpose, helping members see how discount savings and cashback stack up against their monthly spending plan. Visibility turns passive rewards into active savings.
-
Prioritise programmes with no expiry or long expiry windows. Short expiry dates are the single biggest cause of unredeemed reward value. Read the terms before you sign up.
-
Avoid spreading across too many programmes. Holding five different cashback cards with $20 balances each is harder to manage than one programme with a $100 balance. Consolidation makes redemption more likely.
-
Look for referral bonuses. Roopon members earn bonus draw entries for referrals, which compounds the value of membership without additional spending. Many rewards programmes in Australia offer similar referral mechanics worth using.
The trend in 2026 is toward point-of-sale redemption, where rewards are applied at the moment of purchase rather than accumulated and redeemed later. That visibility makes the financial benefit feel real and immediate, which is exactly what drives better budgeting behaviour.
Key takeaways
Cash-equivalent rewards deliver genuine financial value only when recipients understand their mechanics, track their balances, and redeem intentionally rather than letting credits accumulate unseen.
| Point | Details |
|---|---|
| Definition and role | Cash-equivalent rewards function like cash, offering flexible purchasing power across diverse spending needs. |
| Psychological advantage | Gift cards and prepaid cards carry approximately 22% higher perceived value than their face value due to the endowment effect. |
| Earning rates | Cash-back cards typically return 0.5%–3% per transaction, with select categories reaching up to 5%. |
| Tax treatment | Most cash-equivalent rewards are fully taxable; check with a tax agent if received through an employer programme. |
| Maximising value | Combine cashback with experiential rewards, track thresholds, and use budgeting tools to make savings visible. |
Roopon's take on cash-equivalent rewards in everyday finance
The most common mistake people make with cash-equivalent rewards is treating them as a bonus rather than a system. A $15 cashback credit feels trivial in isolation. Tracked across 12 months and redirected toward a specific savings goal, it becomes part of a real financial strategy.
What we have observed is that the programmes delivering the best outcomes are the ones that make rewards visible at the moment they are earned. That is why Roopon combines partner store discounts with weekly prize draw entries rather than just crediting a balance. The discount is immediate and tangible. The draw entry adds anticipation. Together, they create a reward experience that members actually notice and engage with, rather than one that disappears into a bank statement.
The honest caution here is that no reward programme replaces a budget. Cash-equivalent rewards amplify good financial habits. They do not substitute for them. If you are spending more to earn more, the maths rarely works in your favour. The members who get the most from Roopon are the ones already spending intentionally, using the platform to recover value on purchases they were going to make anyway.
The 2026 shift toward point-of-sale redemption is genuinely useful for this reason. When you see the discount applied at checkout, the saving is real and immediate. That visibility changes behaviour in a way that a monthly statement credit simply does not.
— Roopon Team
Roopon: savings and rewards built for Australians
Roopon is built for Australians who want their everyday spending to work harder. Members access exclusive discounts across more than 16 partner stores, earn automatic entries into weekly cash prize draws, and use the Payday Allocator to see exactly how their savings stack up each month.

Whether you are a student managing a tight budget, a nurse looking for exclusive savings on everyday costs, or a tradie stretching your dollar further, Roopon has a membership tier designed around your spending patterns. Members also report odds of winning weekly draws up to 100 times better than larger national competitions. Explore weekly cash prize draws or visit Roopon's student discounts page to see what is available for your situation.
FAQ
What are cash-equivalent rewards?
Cash-equivalent rewards are incentives like prepaid cards, gift cards, and cashback credits that function like cash, giving recipients flexible spending power across a wide range of purchases.
How do cash-back cards work in Australia?
Most cash-back credit cards return 0.5%–3% on everyday purchases, with some categories reaching up to 5%, and typically require a minimum balance of around $25 before you can redeem.
Are cash-equivalent rewards taxable in Australia?
Cash-equivalent rewards received through employment or business programmes are generally treated as taxable income, similar to wages. Consumer loyalty cashback is typically not assessable income, but a registered tax agent can confirm your specific situation.
Why do cash rewards feel less motivating than gifts?
Cash incentives are absorbed into regular expenses, making them invisible as rewards. Research confirms that cash lacks lasting motivational impact compared to experiential or non-cash alternatives, which is why blending reward types produces better results.
How does Roopon differ from a standard cashback programme?
Roopon combines membership discounts across over 16 partner stores with automatic entries into weekly prize draws and a Payday Allocator budgeting tool, giving members both immediate savings and the chance to win cash prizes each week.
Recommended
Our active giveaway
Enter before these draws close — open each giveaway for full details and entry options.
